Bond Selloff Could Mean Outsized Portfolio Changes at Quarter's End
The move comes after government bonds suffered heavy losses while U.S. stocks remained close to record highs
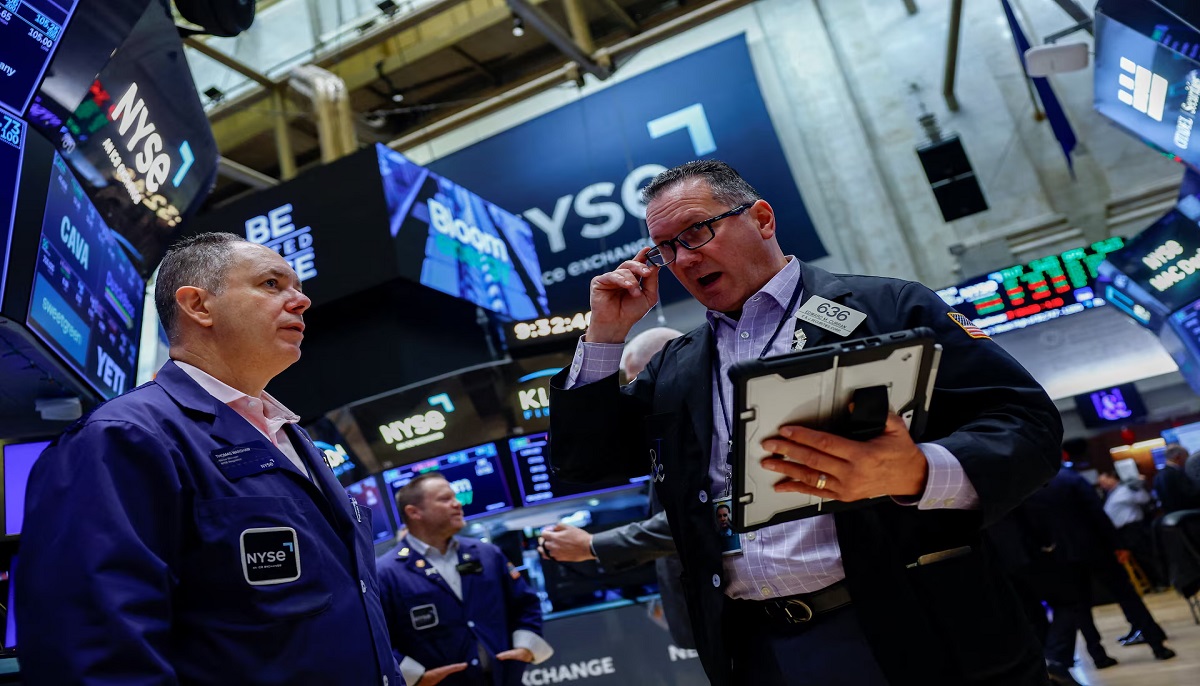
Huge portfolio adjustments are forecast as investors reposition following a turbulent third quarter, with global bonds set for a steep selloff.
It's a response to the sharp sell-off in government bonds, while U.S. shares hovered near record levels. For portfolio's that follow a fixed stock-and-bond target allocation, it meant being nudged out of the intended mix and raising the appeal for investors to liquidate some of their equity holdings to buy more bonds.
The magnitude of the move could be quite large. Goldman Sachs estimated U.S. pension funds would offload roughly $33 billion of equities near the quarter end and pile into bonds. That ranked in the 98th percentile for estimates of quarter-end rebalancing since 2000, and underscores how atypical the expected flows are.
The bond market has seen one of its most challenging stretches in years. The 10-year U.S. Treasury yield hit roughly 5.34% on Thursday, its highest level since 2002, after booking the biggest quarterly climb for the dollaramount in this century during the third quarter. Bond yields increase when prices fall, leading to steep losses for fixed-income investors.
Meanwhile, U.S. stocks have held up relatively well, meaning many portfolios still have more equity than their target allocations. That mismatch can generate mechanical rebalancing flows, as managers buy and sell to get back to their ideal blends.
The quarter is likely to produce one of the largest rebalancing trades in recent memory as volatility has picked up and the deviation from the benchmark and target allocations has become extremely wide, said Jordan Jackson, a global markets strategist at JPMorgan.
Such flows could have effects on markets in the early days of the 4th quarter. The bundling of buys could lend some support to the fixed-income markets while the watering down of equity holdings could weigh on the equity markets. However, the timing and magnitude of asset changes will differ between portfolios as some managers only rebalance once a threshold has been passed.
"The move out of bonds has also shifted the allure for fixed income. Rising yields in Treasury securities give investors higher income potential, though inflation, energy costs, government borrowing and future Fed policy outlook are all factors to keep an eye on."
For investors, the quarter-end moves show how big swings in markets can lead to big flows in the absence of a strategy change. Heading into the beginning of the fourth quarter, investors will be watching to see if rebalancing flows can bring some stability to the bond market and how markets react once most of the portfolio rebalancing flows have occurred.